

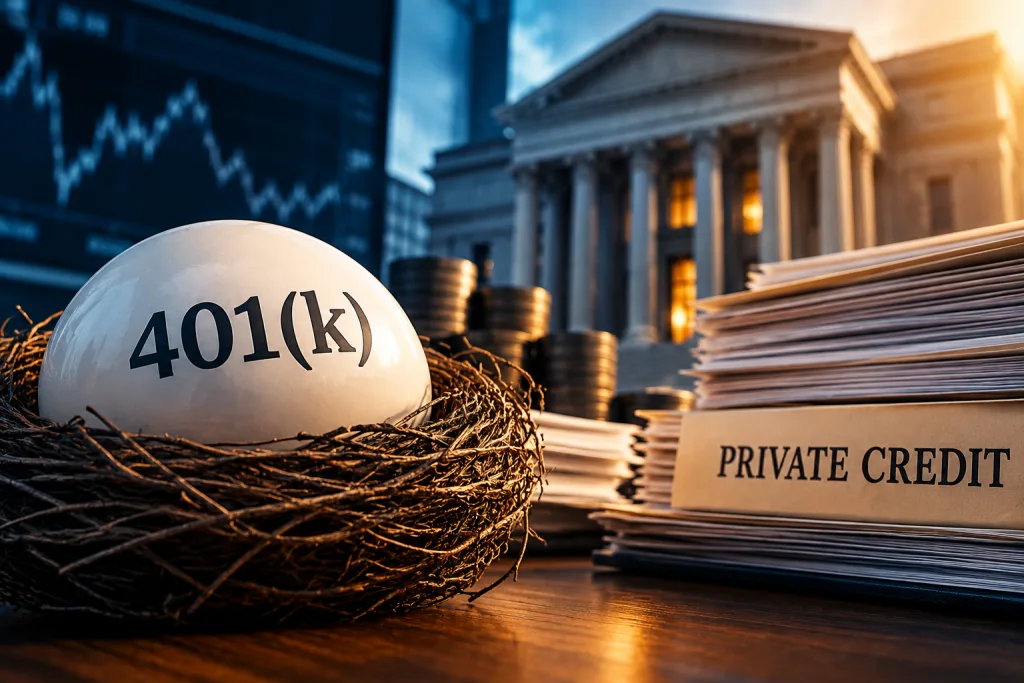
A growing corner of Wall Street is raising concerns about retirement savings.
According to an October 19 report from the Center for American Progress, the global private credit market is estimated at $1.5 trillion to $2 trillion.
Private credit is money lent to businesses by financial firms outside traditional banks.
And it’s becoming increasingly connected to pension funds, insurance companies, and retirement investments.
Now, a proposed federal rule could make it easier for 401(k) plans to offer investments tied to private credit.
But here’s the concern.
Some private credit investments are difficult to value, harder to sell, and exposed to companies that may struggle to repay their loans.
The report found that investors in certain private credit funds have recently requested withdrawals at roughly twice the standard quarterly redemption limit.
In other words, some investors want their money back faster than the funds typically allow.
Why retirees should pay attention
If you’re retired or getting close, access to your savings matters.
Imagine needing money for an unexpected medical bill, home repair, or everyday expenses.
Now imagine discovering that part of your retirement portfolio is invested in something that can’t easily be sold.
That’s one of the concerns surrounding certain private credit funds.
And the exposure doesn’t necessarily stop with your 401(k).
Private credit is also connected to pension funds and insurance companies that provide retirement annuities.
That doesn’t mean these accounts are automatically unsafe.
But it does mean retirees should understand what’s backing their retirement income and how much risk they’re actually taking.
Because when you’ve spent 40 years saving, you don’t want unexpected restrictions or losses when it’s time to use that money.
The lesson: Know what’s protecting your retirement
Just because an investment is offered inside a retirement account doesn’t automatically make it safe.
And just because something is labeled diversified doesn’t mean it’s free from hidden risks.
Before making your next retirement decision, ask yourself:
Do I know exactly where my retirement money is invested?
And:
If I needed access to my savings tomorrow, how much could I actually withdraw?
That’s why diversification matters.
For generations, physical gold and silver have provided another way to diversify beyond traditional financial investments.
Unlike private credit, physical precious metals aren’t loans that depend on a business repaying its debt.
They carry their own risks, including price fluctuations and selling costs, but for some retirees, they may be worth considering as part of a broader retirement strategy.
Wall Street will keep finding new ways to invest your money.
But after decades of saving, protecting your retirement starts with understanding what you own.
Because your retirement savings should work for you, not leave you wondering where your money went.
Read the full Center for American Progress report →
Is your retirement too concentrated in one asset?
Talk through your options in a free, no-obligation strategy call with a Precious Metals Specialist.
Book a Free Strategy CallAmerican Alternative Assets is a precious-metals dealer and does not provide investment, legal, tax, or retirement advice. Decisions regarding the purchase or sale of precious metals are solely the customer’s responsibility and should be made based on the customer’s own research and judgment. Source: Center for American Progress